When fire and smoke alter your home in San Antonio, immediate and professional restoration is crucial to prevent further damage and begin reclaiming your space. At United Water Restoration Group of San Antonio, we specialize in comprehensive fire and smoke damage restoration that prioritizes your family's safety and home's integrity. Don't wait—call (830) 243-6060 now to start the restoration process and reduce the toll fire has taken on your life.
Do you handle fire and smoke damage restoration, or only water damage?
Both. Fire and smoke work is its own discipline with its own standard, ANSI/IICRC S700, covering soot removal, odor control and the cleaning of surfaces flame never touched. Smoke residue sorts into four types — dry, wet, protein and fuel oil — each cleaned differently, so the scope comes from an inspection of your specific loss rather than from a list set in advance. Water damage follows a separate standard, S500, and many fire losses involve both.
Can smoke smell from cigarettes or marijuana actually be removed, or only covered up?
Masking fails because smoke odor is residue sitting on surfaces, not air. Deodorization works in four stages: remove the source material, clean every surface holding residue, treat what remains, then seal what cannot be cleaned. ANSI/IICRC S700 puts source removal before any sealing, and that holds for tobacco or cannabis alike. The EPA and CDC describe residual tobacco smoke settling into walls, carpet and dust long after the smell fades. Heavy saturation often means replacing some materials, and every house differs.
Can you keep the smell from spreading to the rest of my house while you work?
Containment comes first, before any cleaning. The work area is sealed with sheeting and held under negative pressure so air moves into the zone rather than out into the rest of the home, then exhausted through HEPA filtration, which captures 99.97 percent of particles at 0.3 microns, the hardest size to catch. IICRC S520 describes the same containment principle for mold work. How much enclosing a home needs, and how completely it holds, depends on how far residue already traveled.
How do I tell whether a smell is on the surface or coming from inside the wall?
Press a damp white cloth on a hidden patch. If residue transfers and that spot goes quiet, it was surface odor. If it returns a day or two after cleaning, or sharpens when the heating and cooling system runs, the source sits in a wall cavity, insulation or ductwork. ANSI/IICRC S700 treats odor as residue to be located, not covered, and protein residue leaves almost no visible mark while carrying strong odor, so a cloth coming back clean does not rule it out.
Is the estimate free, or do you charge to come out and inspect?
Having someone come out and look at the damage carries no charge in most cases. That visit is what sets the scope: which of the three water categories in ANSI/IICRC S500 applies, how far it migrated, and what has to be dried. A written estimate is separate work, and depending on the office, preparing one may carry a fee. You are told what is chargeable before anything is charged.
When can someone come out, and can work start on the first visit?
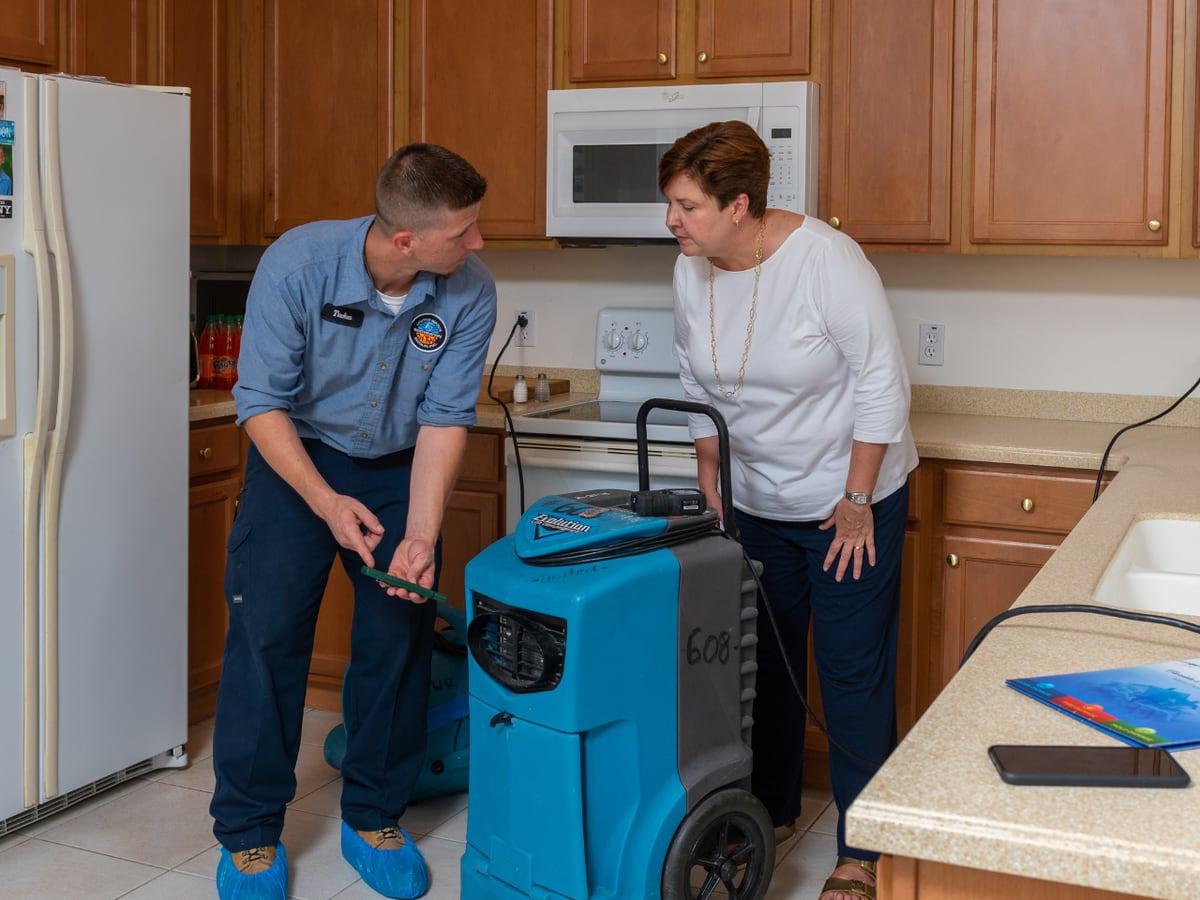
The phone is answered around the clock, and on that call you are given an honest arrival window for your specific address rather than a stock answer. The visit is not a sales appointment — crews carry extraction and drying equipment, so when the situation calls for it emergency work can begin on the first visit: standing water pulled out, air movers and dehumidifiers set, and the wet area mapped against a dry standard under ANSI/IICRC S500.
How much does restoration cost?
Nobody can price a loss honestly without seeing it. The number is built from measured facts: the square footage affected, how much material has to come out, the water category — 1 through 3 under ANSI/IICRC S500 — and how many days of drying equipment the structure needs. Most carriers settle water claims against Xactimate's regional price list, the same line-item data a properly written estimate uses. A contained spill and a loss that soaked three rooms are not in the same range.
What kinds of damage and cleanup do you handle?
Water damage is the bulk of the work, across all three categories ANSI/IICRC S500 defines — clean supply water, gray water, and sewage. Fire and smoke work covers soot, char and odor. Mold remediation follows IICRC S520. Storm and wind damage, contents cleaning for furniture and belongings, and the reconstruction that puts drywall, flooring and cabinetry back are all in scope, though what each office handles in-house varies. Plumbing, roofing and electrical repairs are separate trades.
Can you give me a price range over the phone, or quote from photos or a report I already have?
Photos and a report you already have are genuinely useful — bring them, they shorten the visit. What they cannot do is produce a number, because what drives the scope is moisture inside material you cannot photograph. ANSI/IICRC S500 works from meter readings against a dry standard in the same building, and from the water category: Category 1 can often be dried in place, while Category 3 means contaminated material comes out instead. A range quoted sight-unseen is a guess, and guesses move.
Do you work with insurance companies — can you bill my insurer directly, or do I pay and get reimbursed?
Direct billing to the carrier is common on covered losses, arranged once the claim number and adjuster are in hand, so you are not fronting the whole job. Carriers generally review water losses as Xactimate line items rather than a lump sum. How it runs depends on your policy — some issue payment to you and your mortgage holder rather than the contractor, which changes the paperwork but not the scope. You are told which arrangement applies before work starts.
Do I need to call a plumber first, or do you stop the leak too?
Turning the water off at the main comes first, if you can reach it safely, because that is what stops the loss from growing. Repairing the failed pipe, fixture or roof is plumbing or roofing work and usually a separate trade. Mitigation does not have to wait on that repair: ANSI/IICRC S500 treats source control and structural drying as distinct steps, so extraction and drying can start while the plumbing is still being scheduled.
What should I do right now, before the crew arrives?
Shut off the water at the main and kill power to the affected area at the breaker if you can do it from a dry spot — never standing in water. Lift what you can off wet flooring, especially anything wood, paper or upholstered, and pull rugs up. Blot or wet-vac standing water if it is clean. The clock is real: EPA guidance is that wet material dried in the first 24 to 48 hours will in most cases not grow mold.
Will I get a written estimate before work starts, and how soon after the visit?
Emergency mitigation usually starts on a signed work authorization covering extraction and drying, because waiting on paperwork while water sits makes the loss bigger. The line-item estimate follows, and when it lands depends on the size of the loss and whether a carrier is reviewing it; the office can give you a realistic date on the call. The daily moisture readings ANSI/IICRC S500 requires are what justify each line, and a scope that grows gets a revised estimate.
What are your hours — do you work nights and weekends, and does that cost more?
The phone is answered around the clock, including nights, weekends and holidays, because a loss found at night only gets worse while it sits, and on that call you are given an honest arrival window for your address. After-hours labor is a recognized line item in Xactimate, the pricing data carriers settle against, so where it applies it shows on the estimate like everything else rather than as a surprise. Whether it applies to your situation at all is said plainly up front.
If this isn't something you handle, can you point me to someone who does?
Ask on the call and you will get a direction rather than a dial tone. Some work genuinely belongs elsewhere: a plumber for the pipe itself, a roofer for the roof, an HVAC contractor for a condensate or duct problem, and for mold an independent indoor environmental professional, since IICRC S520 flags the conflict of interest when the same firm both assesses and remediates. Saying so plainly is more use to you than a visit that goes nowhere.
Does homeowners insurance cover this, and will I still owe my deductible?
Most policies cover sudden, accidental water damage and exclude damage that developed gradually, and the wording varies from policy to policy — read your own and ask your adjuster directly rather than assuming it either way. Your deductible applies regardless and cannot be waived, discounted or absorbed into the invoice. Anyone offering to do that is describing insurance fraud.
Should I call my insurance company first, or get you out first — and does the work wait for their approval?
Either order works, and many people do both back to back. What should not happen is drying waiting on a claim decision. EPA guidance puts the mold window at 24 to 48 hours for wet material, and most policies place a duty on the homeowner to prevent further damage, which is why emergency mitigation proceeds on your own authorization while the claim is still being opened. The readings and photos taken at the start are what the adjuster reviews later.
Is anything due up front, what payment methods do you take, and do you offer payment plans?
On an insurance claim the usual pattern is that your deductible is collected and the carrier's payments cover the rest as work is approved, which usually means no large sum is due before mitigation begins. Self-pay jobs are structured differently and often staged between drying and repairs. Card, check and ACH are normally accepted, some offices can arrange terms, and any processing fee is disclosed before you pay. What applies to you is in writing before you sign.
What information do you need from me to get started?
The basics are the address and how to get in, a callback number that reaches you, what you know about the source and when it started, and whether power and water are still on. If a claim is open, add the carrier, policy and claim number and the adjuster's details. Photos taken before anything was moved matter more than they look: ANSI/IICRC S500 scoping rests on documented conditions, and the earliest record cannot be recreated later.
Will you document the damage for my claim and deal with my adjuster, or do I handle that?
Documentation is part of the job, not homework for you. Moisture readings, photographs, affected material measurements and daily drying logs are produced as the work goes, because ANSI/IICRC S500 expects drying to be verified against a dry standard rather than declared. You can ask for copies of all of it. Discussing scope with an adjuster who is limiting it is normal, though the carrier makes the coverage decision and the policy sets the limits.
Is it safe for my family to stay in the house while this is going on?
That depends on what the water is and what it reached, and it is assessed first. ANSI/IICRC S500 sorts water into three categories, and Category 3 — sewage or heavily contaminated water — is treated as a containment job with restricted entry. The EPA and CDC describe mold and sewage exposure as a greater concern for infants, older adults and people with asthma or weakened immune systems. Clean-water losses confined to one area often allow normal occupancy; ask about your own rooms.
Can you still help me if I don't have insurance, or don't want to file a claim?
Self-pay customers are welcome, and plenty of people choose that route deliberately when the likely scope sits near or under their deductible or they would rather not have a claim on record. The work itself does not change — the same ANSI/IICRC S500 drying standard, the same readings, the same verification. What changes is the paperwork and the payment arrangement, which the office walks you through, including how the scope can be staged if that helps.